Mistakes that Startups make in a Financial Model
Startup financial model mistakes: 9 errors investors catch first
An investor does not need an hour with a startup financial model. A few minutes is enough. They change a growth rate, check whether the balance sheet still balances, and ask how many months of cash the company has. A model that fails those checks loses credibility before the conversation reaches the product.
Most failures are not exotic. They repeat across founder-built files: growth typed in instead of earned, inputs buried in formulas, cash confused with revenue, one scenario only. This guide lists nine of them, shows how each looks from the investor’s side, and gives a fast check and fix for each.
Why model mistakes cost more than the number
Nobody expects a seed-stage forecast to be right. Investors discount projections by default. What they read is whether the founder understands how the business works: what drives growth, what it costs, and how long the cash lasts.
A mistake that breaks that logic does the damage. Costs that stay flat while revenue triples tell the investor the founder has not yet worked out the links. A wrong number is forgivable. A model that cannot be trusted is not.
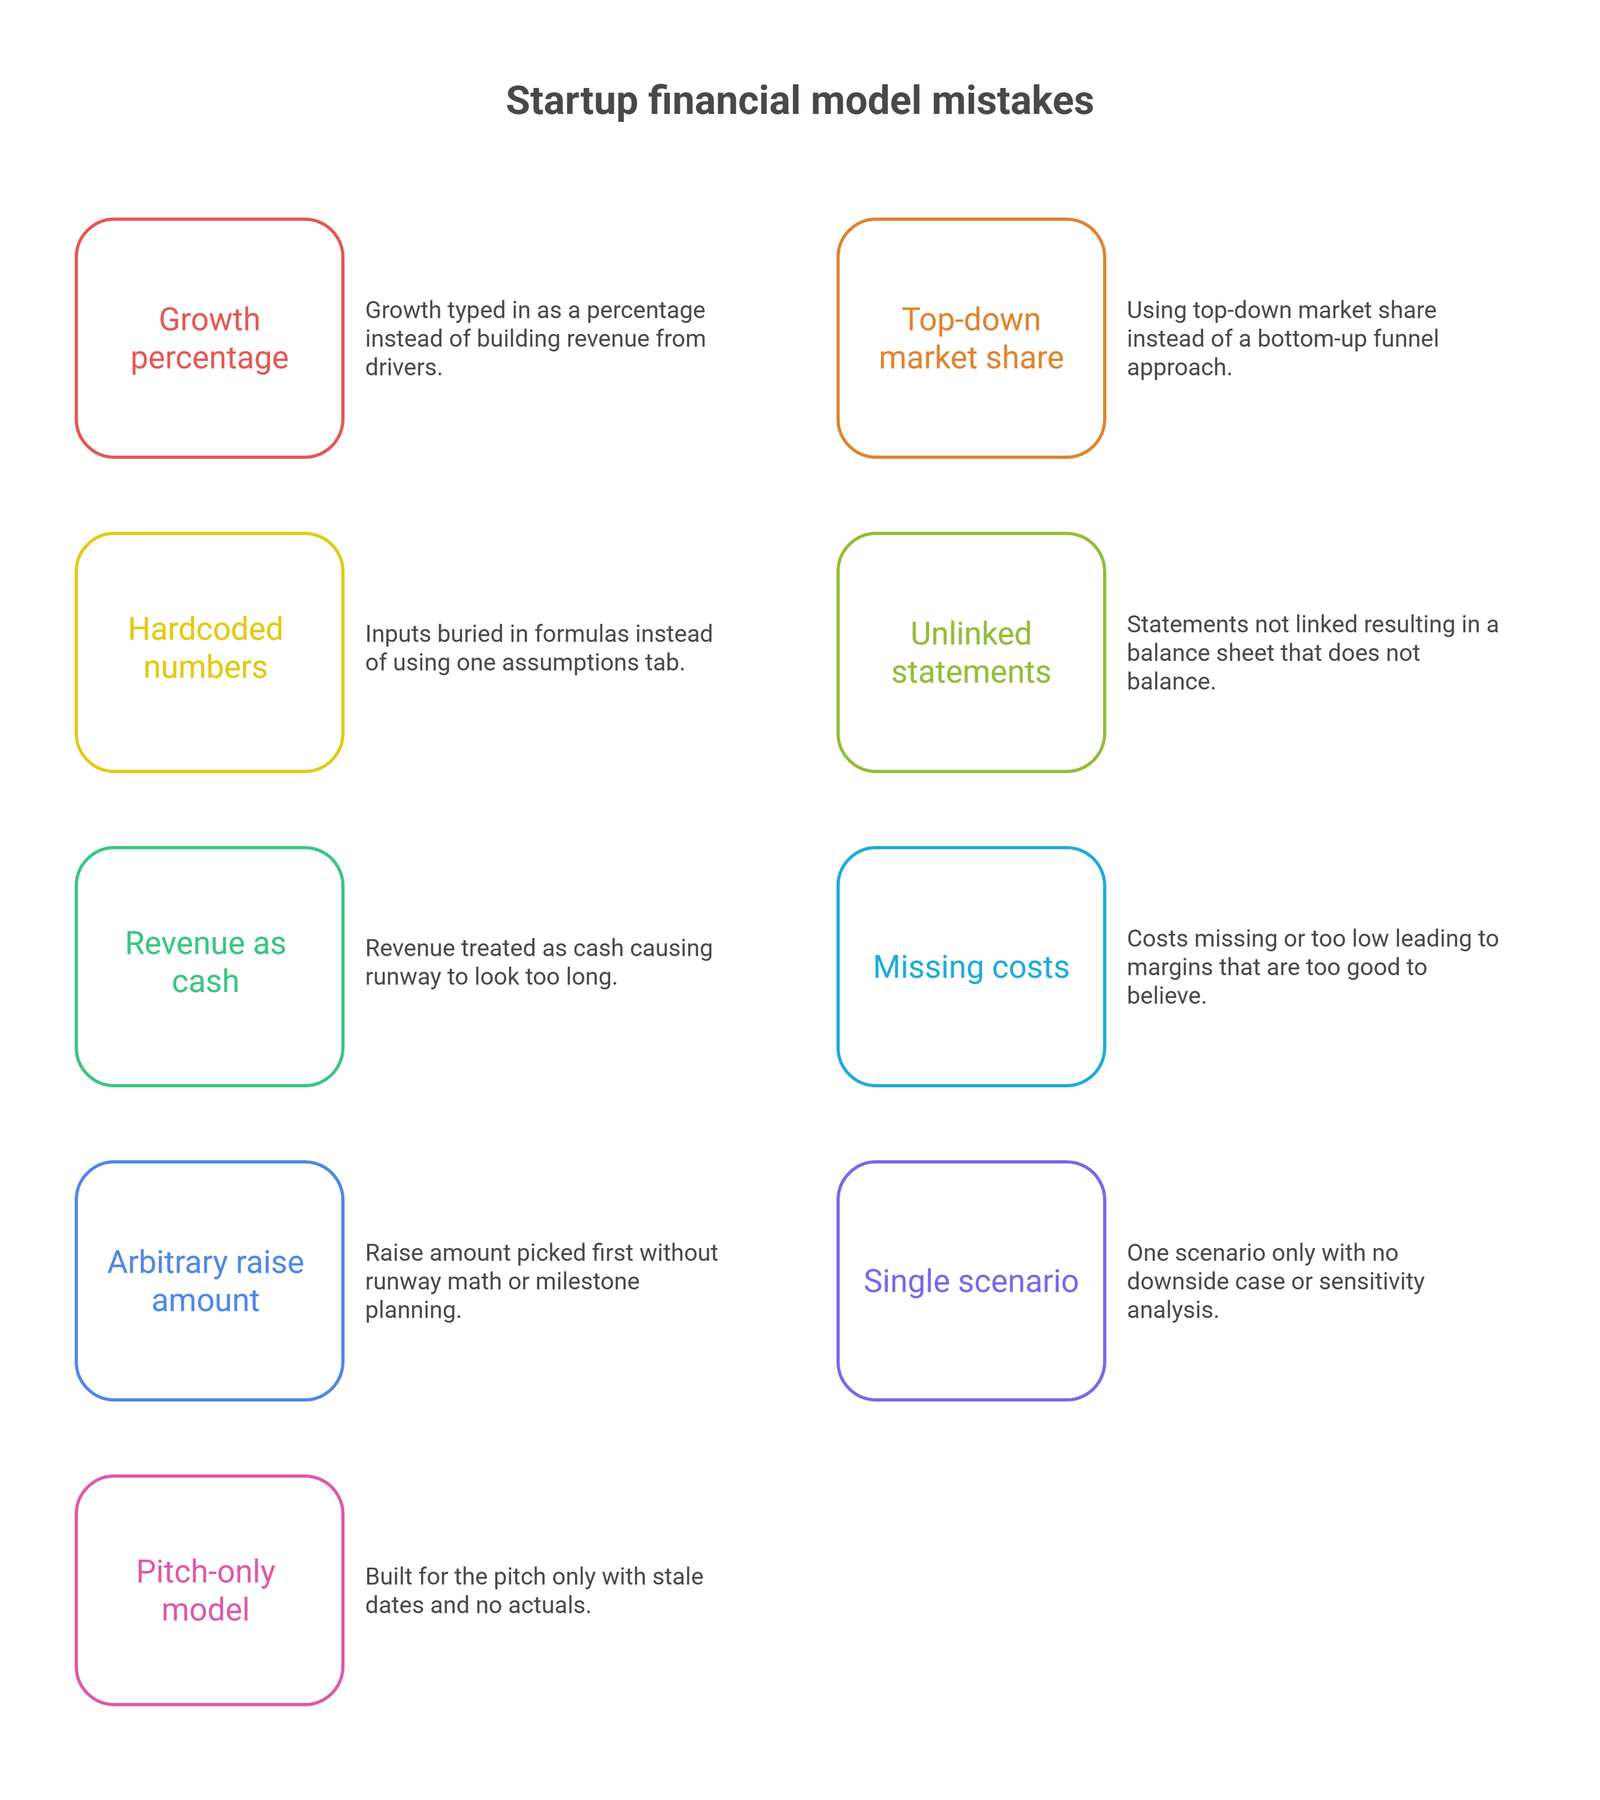
| # | Mistake | What the investor sees | Fix |
| 1 | Growth typed in as a percentage | Hockey stick with flat costs | Build revenue from drivers |
| 2 | Top-down market share | “We only need 1% of the market” | Bottom-up funnel, top-down as a check |
| 3 | Hardcoded numbers | Inputs inside formulas | One assumptions tab |
| 4 | Statements not linked | Balance sheet that does not balance | Link statements, add check rows |
| 5 | Revenue treated as cash | Runway that looks too long | Model collections and payment timing |
| 6 | Costs missing or too low | Margins too good to believe | Loaded headcount, variable costs |
| 7 | Raise amount picked first | A round size with no runway math | Work backward from milestones |
| 8 | One scenario | No downside case | Base, best, worst and sensitivity |
| 9 | Built for the pitch only | Stale dates, no actuals | Monthly update against actuals |
Mistake 1: growth typed in as a percentage
A founder starts at $5,000 of revenue in month one and applies 20% growth for 24 months. Month 24 shows roughly $331,000. The line looks excellent and explains nothing.
Marketing spend, sales hires and support cost sit flat or rise slowly while revenue multiplies about 66 times. Investors read that as a founder who has not worked out what causes growth.
The fix is to make revenue the output of drivers: ad spend, cost per click, signup rate, conversion rate and price. Quick check: can any revenue cell be overtyped directly? If yes, it is a typed-in number and not a forecast.
Mistake 2: top-down market share
“The market is $10 billion and the company needs 1%” is a sentence, not a forecast. It says nothing about how the first 100 customers are found, what they cost, or how long they take to close.
Top-down numbers are fine for showing the market is large enough. They should not be the revenue line. Build the forecast from a bottom-up funnel, then use the top-down figure as a check. If year-three revenue implies an implausible share of the market, one of the two is wrong.
Quick check: for each customer group, can the model name the channel, the conversion rate and the cost per customer?
Mistake 3: hardcoded numbers and buried assumptions
A tax rate typed into a formula, a salary raise hidden in a cell, a price copied into four tabs. Each one stays invisible until an investor changes something and half the model refuses to move.
Overbuilt files have the same problem. Dozens of tabs that only the builder can follow make errors hard to find, and nobody else will update them.
The fix is one assumptions tab, inputs in a single color, formulas with no typed numbers, and a short note on the source and date of each assumption. Quick check: use the spreadsheet’s Go To Special, Constants option to find typed numbers in cells that should hold formulas.
Mistake 4: statements that do not link
The income statement shows a profit, the cash flow statement was pasted in, and the balance sheet is out by a few thousand dollars. An out-of-balance balance sheet is one of the fastest ways to lose an investor’s confidence. It proves a formula is broken and nobody noticed.
Link the three statements so that cash comes from the income statement and balance sheet movements, not from typed figures. Oak’s guide to building an integrated three-statement financial model shows how.
Add two check rows: assets minus liabilities and equity, and cash on the cash flow statement minus cash on the balance sheet. Both should read zero every month, in every scenario.
Mistake 5: revenue treated as cash
A customer pays $1,200 on an annual plan. That is $1,200 of cash today but only $100 of revenue a month. Another customer is invoiced and pays in 60 days, so revenue arrives first and cash arrives later.
Models that ignore this show runway that is too long or too short. The gap is widest for hardware, e-commerce with inventory, and services with long payment terms.
Add collection days, payment terms, deferred revenue and inventory. Quick check: pick one month and trace a single customer from invoice to bank balance.
Mistake 6: costs missing or too low
Costs go missing in predictable places: payroll taxes and benefits, payment processing fees, hosting and support that grow with users, contractors during a growth push, legal and accounting, and a founder salary set at zero.
Investors know typical margins for a sector. A gross margin well above peers prompts a question, and the founder needs an answer.
Use fully loaded headcount, model variable costs as a percentage of revenue or a cost per unit, and add a contingency line. Quick check: compare gross margin and payroll share with the sector, and explain every gap.
Mistake 7: raise amount picked first
A founder decides to raise $2 million because similar startups did. The model never shows what the money buys or when it runs out.
Work backward instead. Decide the milestone the next investor will want, such as customers, revenue or a product launch. Model the cost of reaching it, then add a buffer for the time fundraising takes.
For example, $1.2 million at $50,000 of monthly burn lasts 24 months. If a raise takes about six months, the milestone has to be reached by month 18. If the plan only gets there in month 22, the round is too small or the plan is too slow.
Quick check: does the model state the month cash runs out and the milestone reached before that month?
Mistake 8: one scenario and untested assumptions
A single case means the model only works if everything goes well. Investors will run their own downside, so the founder should run it first.
Build base, best and worst cases behind one switch. Then run sensitivity on the inputs that move cash the most: conversion rate, churn, customer acquisition cost and hiring dates. Oak’s sensitivity analysis template is one way to set it up.
Suppose halving the conversion rate cuts runway from 24 months to 15. The founder now knows which assumption needs the most evidence before the pitch.
Mistake 9: built for the pitch and never updated
Many founders treat the model as homework for the data room. Within a quarter, actuals drift from the plan, and nobody notices because nobody opens the file.
Stale models show their age. The last-updated date is months old, forecast months have passed with no actuals entered, and the assumptions contradict what the founder says in the pitch.
Update the model monthly: enter actuals, compare them with the forecast, and revise the assumptions that were wrong. As a company matures, investors expect the forecast to track real monthly revenue closely, and only a model in regular use gets there. Quick check: is the first forecast month next month, or a date already in the past?
A 10-minute self-audit before sending the model
Run these checks before the file goes to an investor:
- Both check rows (balance sheet and cash tie-out) read zero in every month and every scenario.
- Change the conversion rate and confirm that revenue, costs and cash all move.
- Search for typed numbers inside formulas.
- Switch to the worst case and read the runway.
- Trace one customer from signup to cash.
- Compare gross margin and headcount cost with the sector.
- Confirm the raise amount reaches the stated milestone with six months to spare.
- Check that the first forecast month is next month.
- Ask someone who did not build the model to find one error.
Frequently Asked Questions
What are the most common startup financial model mistakes?
Growth typed in as a percentage, top-down revenue, hardcoded inputs, statements that do not link, cash timing ignored, and missing costs. Together they account for most of the models that fall apart under questions.
How do investors check a startup financial model?
They change an input and watch what moves, check that the balance sheet balances, compare margins with the sector, and read the runway against the stated milestones. Most of this takes a few minutes.
Is an optimistic forecast a mistake?
Investors expect optimism and discount it. The mistake is a forecast with no driver logic behind it, because that shows the founder does not know what causes growth.
How accurate does a startup financial model need to be?
At pre-seed and seed, nobody expects accurate revenue. The structure has to be sound: drivers, linked statements and a clear runway. Accuracy matters more with each round, when investors compare forecasts with actual results.
Can a template cause these mistakes?
Yes. A template with placeholder inputs, or a revenue logic that does not fit the business, produces polished but wrong numbers. Oak’s startup financial model guide lists what to check before using one.
Should a founder build the model or hire help?
Many founders build the first version. Once the model supports a raise, an outside review catches errors a builder cannot see. The same applies when a startup should hire a CFO: the model is often the first thing a CFO rebuilds.
Building the model to be questioned
Every mistake on this list comes from the same habit: building the model to look finished instead of building it to be questioned. A model that invites an investor to change inputs and still behaves is rarer than a polished one, and it is the one that survives diligence.
Oak builds and stress-tests startup financial models for founders preparing to raise. See Oak’s startup financial model services, or ask about CFO services for startups to keep the model accurate after the round closes.