


Real Estate Investment Model: From Property NOI to Investor Returns
Real estate financial model: how a 5.8% cap rate becomes a 7.5% IRR
A $6 million apartment building shows a 5.8% cap rate. The seller’s pro forma looks fine. Then the model runs, and the equity earns a 7.5% IRR. That is barely above what the building earns with no loan at all.
The pro forma never showed that gap. It shows one scenario, written by the person selling.
A real estate financial model forecasts a property’s income, costs, debt, and exit. Then it changes the assumptions to see what breaks. This guide builds one in the order a model is built. It ends with a tested deal, the four strategies that change the structure, and the model that fits each property type.
What a model does that a pro forma cannot
A pro forma answers one question: what if everything goes to plan? A model answers a harder one: what if it does not?
The difference shows up in three places:
- Inputs are separate from results. Change one assumption and every return updates.
- Debt is modeled, not assumed. The loan can help returns or hurt them.
- Exit is tested, not guessed. The sale price depends on a single rate that nobody can know today.
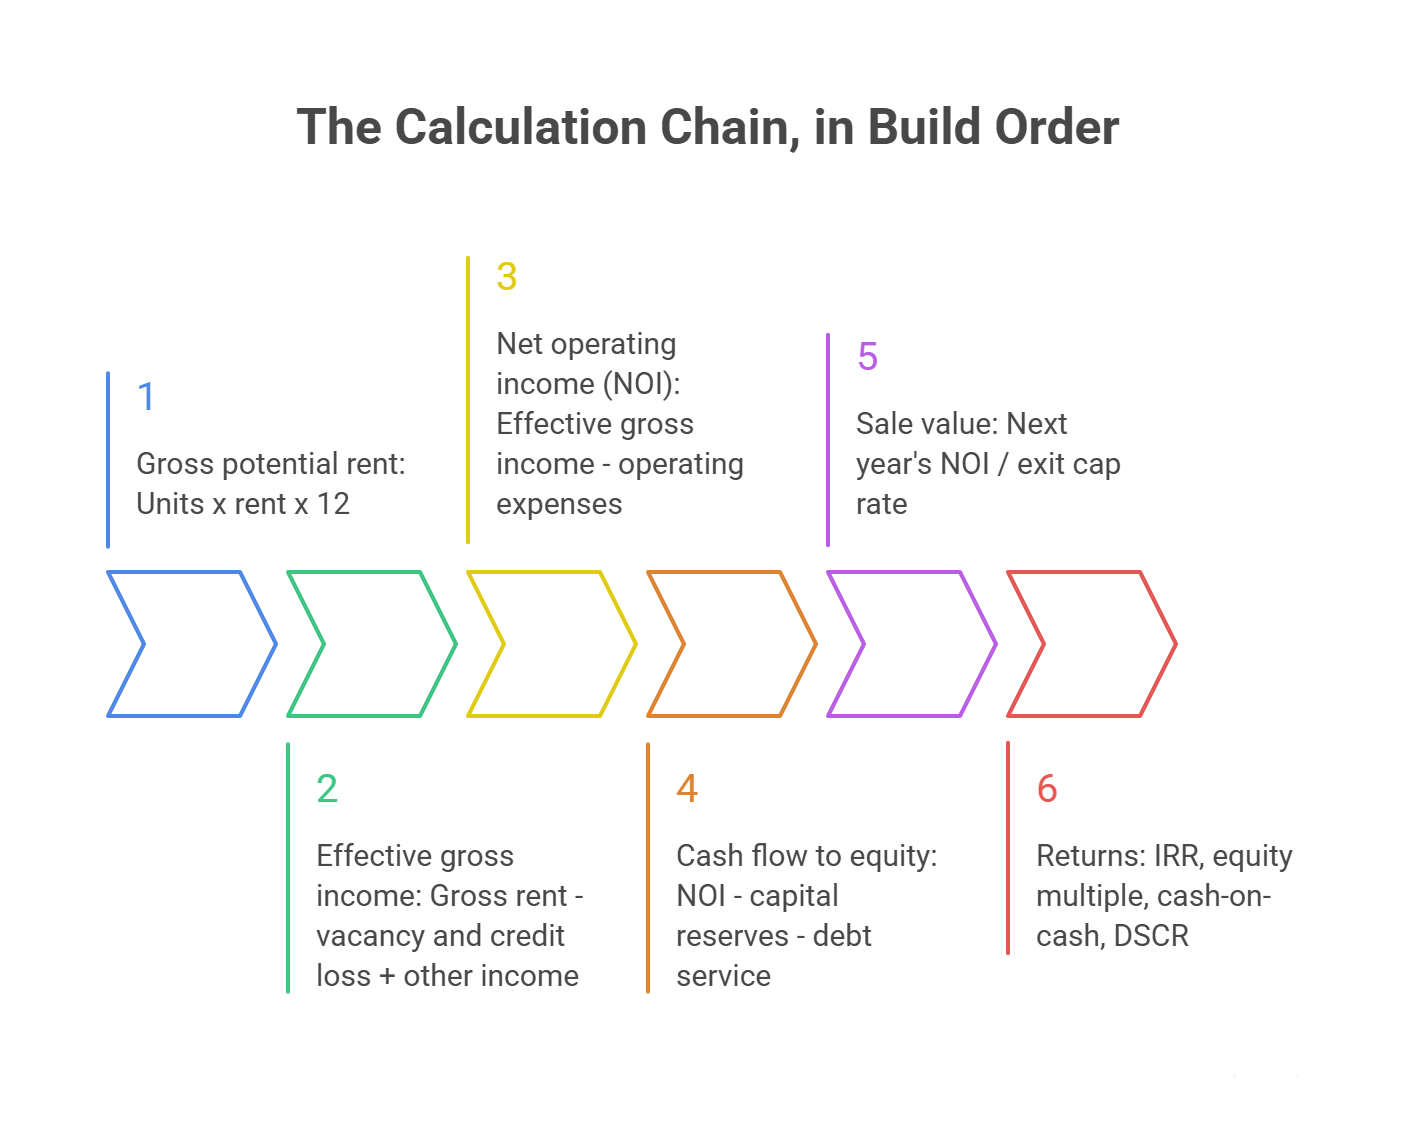
The calculation chain, in build order
Every model follows the same chain. Build it in this order and errors stay easy to find.
| Step | Calculation | What to watch |
| 1. Gross potential rent | Units x rent x 12 | Use in-place rents, not asking rents |
| 2. Effective gross income | Gross rent – vacancy and credit loss + other income | Test vacancy above the market average |
| 3. Net operating income (NOI) | Effective gross income – operating expenses | Decide where reserves sit, then stay consistent |
| 4. Cash flow to equity | NOI – capital reserves – debt service | Debt service falls here, not in NOI |
| 5. Sale value | Next year’s NOI / exit cap rate | Selling costs and loan payoff come out after |
| 6. Returns | IRR, equity multiple, cash-on-cash, DSCR | Read them together |
Capital costs such as capex, tenant improvements, and leasing commissions sit below NOI. Whether reserves count inside NOI is a choice. The rule is to treat the purchase price, the exit value, and any cap rate comparison the same way.
Sale value uses the NOI of the year after the sale. A buyer pays for the income they will receive, not the income you already collected.
A tested deal: 40 apartments, $6 million
The numbers below are hypothetical. They show how income turns into returns.
| Line | Assumption | Result |
| Gross potential rent | 40 units x $1,300 x 12 | $624,000 |
| Vacancy and credit loss | 7% | -$43,680 |
| Other income | Laundry and parking | $24,000 |
| Effective gross income | $604,320 | |
| Operating expenses | Taxes, insurance, repairs, payroll, utilities | -$255,000 |
| Year 1 NOI | $349,320 | |
| Purchase price | $6,000,000 | |
| Going-in cap rate | $349,320 / $6,000,000 | 5.82% |
| Loan | 65% of price, 6.25%, 30-year amortization | $3,900,000 |
| Annual debt service | $288,156 | |
| DSCR, Year 1 | $349,320 / $288,156 | 1.21 |
| Equity required | Price + $150,000 closing and reserves – loan | $2,250,000 |
Rents grow 3% a year and expenses 2.5%. Reserves are $12,000 a year, held outside NOI. The building sells at the end of Year 5 at a 6.25% exit cap rate, with 2% selling costs.
Year 6 NOI is $412,063. Divide by 6.25% and the sale price is $6,593,015. After selling costs and the $3,640,152 loan balance, equity receives $2,821,002.
The result:
- Levered IRR: 7.5%
- Equity multiple: 1.42x
- Unlevered IRR: 6.7%
- Year 1 cash-on-cash: 2.2%
Debt added only 0.8 points of IRR. The reason is negative leverage. The loan has a constant of 7.39%, which is annual debt service divided by the loan amount. The building yields 5.82%. Each borrowed dollar costs more than it earns today.
So this deal does not pay through cash flow. It pays through NOI growth and the exit price. A pro forma showing only the cap rate would hide that.
Stress test: the exit cap rate does the damage
Now change the assumptions that matter most. The table shows levered IRR, with the equity multiple in brackets.
| Rent growth | Exit cap 5.75% | Exit cap 6.25% | Exit cap 6.75% | Exit cap 7.25% |
| 1% | 2.7% (1.14x) | -1.6% (0.93x) | -6.0% (0.75x) | -10.7% (0.59x) |
| 3% (base) | 11.2% (1.67x) | 7.5% (1.42x) | 4.0% (1.20x) | 0.4% (1.02x) |
| 4% | 14.8% (1.95x) | 11.4% (1.68x) | 8.0% (1.45x) | 4.8% (1.25x) |
Three readings stand out:
- Each half point on the exit cap moves IRR by about 3.5 points in the base case.
- Equity breaks even on IRR at an exit cap near 7.3%. Above that, the equity loses money over the hold.
- A 10% IRR needs an exit cap near 5.9%. That is below the going-in cap rate. It assumes buyers pay more per dollar of income in five years.
Debt cost and vacancy matter too. The same deal at other settings:
| Change | Levered IRR | DSCR |
| Loan rate 5.25% | 9.1% | 1.35 |
| Loan rate 6.25% (base) | 7.5% | 1.21 |
| Loan rate 7.25% | 6.0% | 1.09 |
| Vacancy 5% | 9.6% | 1.26 |
| Vacancy 10% | 4.2% | 1.15 |
| Vacancy 12% | 1.8% | 1.10 |
At a 7.25% rate, DSCR falls close to the 1.1 to 1.2 range many lenders treat as a floor. The model shows a lender problem before the lender does.
A common rule of thumb sets the exit cap 25 to 50 basis points above the going-in rate, because the building will be older at sale. Use a lower number only when renovations clearly justify it.
Four strategies, four structures
The strategy decides how the model is built. It is not just a label on the inputs.
| Strategy | Income at start | What the model must capture | Main risk |
| Acquisition | In-place rents | Rent growth, expenses, exit | Overpaying relative to NOI |
| Value-add | Reduced during work | Renovation spend, lost rent, higher rents after | Cost overruns and slow lease-up |
| Development | None | Land, construction draws, lease-up, stabilization | Timing and cost of everything |
| Fund or portfolio | Blended | Fund-level returns and fees on top of each asset | Errors repeated across assets |
Acquisition models are the usual starting point. The price and rents are known. Development models carry the most risk, because debt and equity are drawn over time and no income exists until the building is leased.
Waterfalls: why outside capital changes the model
Alone, you keep all the cash. With outside investors, cash follows an order set in the deal terms.
A typical waterfall pays investors a preferred return first. Once that hurdle is met, the sponsor receives a promote, which is a larger share of profit above the hurdle. The model must track cumulative payments against each partner’s terms every period.
This is where many models fail. They split cash flow by ownership percentage, which ignores the order of payment.
Which model fits which property
Strategy applies to every property type. The risks differ.
| Property type | What drives returns | Oak model |
| Hotel | Daily occupancy and rate, seasonality, brand fees, renovation cycles | Hotel acquisition financial model |
| Commercial and industrial | Lease terms, tenant credit, expiry dates | Commercial and industrial acquisition model |
| Single-family | Resale timing, renovation overruns | Single-family real estate model |
| Rental portfolio | Scheduled versus collected income, management cost as the portfolio grows | Rental property financial model |
| Apartments and multifamily | Thin per-unit margins, so expenses matter most | Apartment rental financial model |
A hotel has no lease to rely on. One departing tenant can sink an office building. Pick the model built for the risk you actually carry.
Seven mistakes that weaken a model
- Quoting only the cap rate. It ignores debt and capital costs.
- Using an optimistic exit cap. It assumes the building gains value per dollar of income.
- Mixing NOI definitions. Reserves treated differently at entry and exit distort returns.
- Running one scenario. A single outcome shows no downside.
- Ignoring peak equity. Renovation and capex draws can require more than the first check.
- Tracking the waterfall loosely. Payments must follow each partner’s terms.
- Hardcoding numbers inside formulas. Every input belongs in one assumptions tab.
Frequently Asked Questions
What is a real estate financial model?
It is a spreadsheet that forecasts a property’s income, expenses, financing, and sale. It then calculates returns such as IRR and equity multiple. Its main job is to test how returns change when assumptions change.
Is cap rate or IRR the better metric?
They answer different questions. Cap rate is a one-year snapshot of income against price. IRR covers the whole hold, including timing, so it compares deals with different timelines more fairly.
What is negative leverage?
It happens when the loan constant is higher than the property’s cap rate. Borrowing then lowers current cash yield. Returns depend on income growth and the exit price. The tested deal above shows it.
Should NOI include capital reserves?
Either way can work. What matters is consistency across the purchase price, the exit value, and any cap rate you compare against. Check how comparable sales define NOI as well.
How far out should the model project?
Acquisition models commonly use five to ten years. Development models run longer to cover construction, lease-up, and a stabilized hold.
Can one model handle a single property and a portfolio?
Yes, if it is built that way from the start, with clean assumption tabs and consistent formulas. Stretching a single-property model into a ten-property portfolio later usually adds errors that are hard to trace.
A model is a stress test
The investors who decide well are not the ones with the largest spreadsheets. They are the ones who find the weak assumption before the capital moves.
Oak Business Consultant builds real estate models for acquisition, value-add, development, and portfolio strategies. Explore Oak’s real estate financial modeling services to talk through the model your next deal needs.


